Finat unveils European industry trends
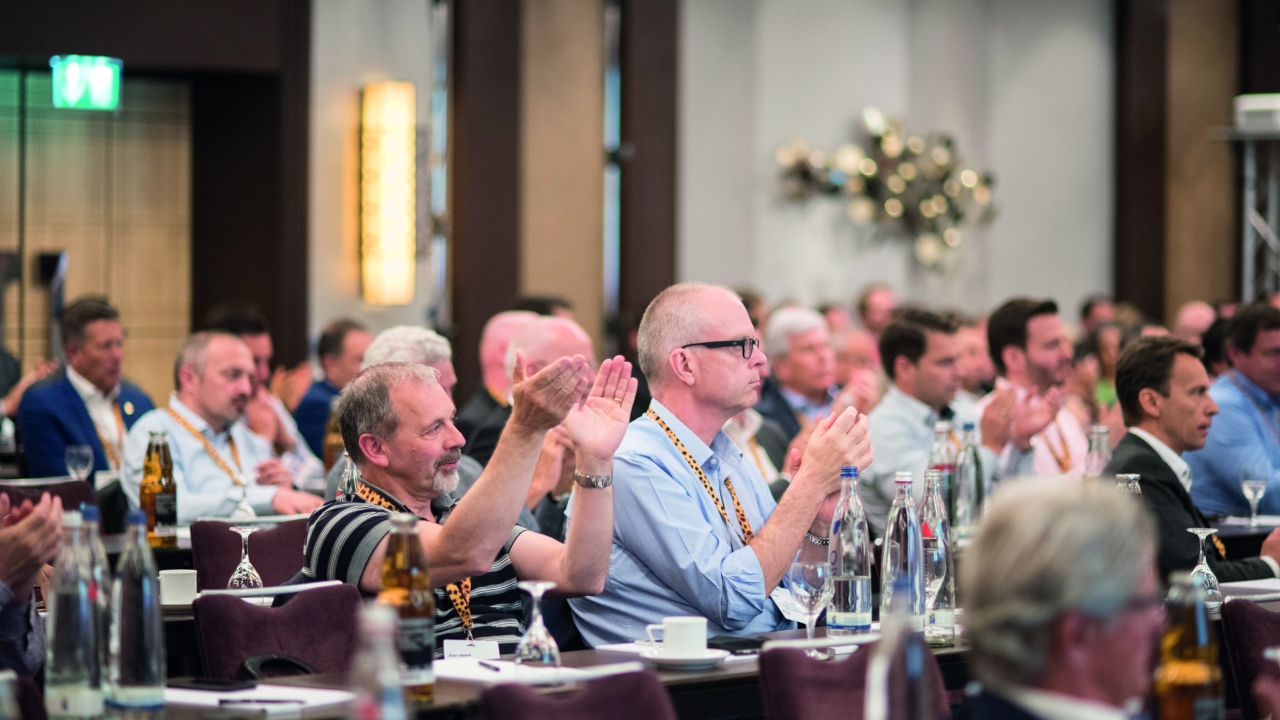
Finat’s new ‘ELF’ format annual meeting, held in Berlin this year, was a great success, with a wide range of sessions of practical use to converters, suppliers and end users, as well as the usual unparalleled networking opportunities. There was still a disappointing number of label converters attending, but that is something that new president Chris Ellison has promised will be at the top of his agenda.
Industry 4.0
The prime topic addressed by the opening session of the forum was change – the fourth industrial revolution – and the aspects relevant to the label industry. Michael Jackson, an expert in change and a renowned international speaker, summarized those challenges as computing, communication, connectivity, collaboration and convergence, and defined them one by one in a presentation that brought clarity and a change in thinking about change to assembled delegates. ‘Most of our ancestors were born and died in a world that looked the same,’ he said. ‘My grandparents’ generation was the first to see change happening around them, and my generation has seen more change than any other.’ He encouraged delegates to try out new directions, personally and in the business environment, defying the fact that humans are creatures of habit. His message was, ‘If you are not disrupting your industry, you are rapidly becoming outdated.’
He proposed a new central focus – on the future destination of a business – enabled by an energizing concept of ‘effective togetherness’, embracing objectives, information, networks and teams, because ‘People united by a real deliverable, and visibly-manageable common purpose, deliver more effectively.’
Jan Denys, labor market expert at global recruitment company Randstad Group, examined in depth the strategic question of employer branding at such a time of change as the fourth industrial revolution – Industry 4.0. There are new employee profiles, created by new forms of work, and which demand new talent and skills in such arenas as social media, design, innovation and transdisciplinary thinking. Denys shared his company’s research into the key job attributes identified by potential employees worldwide, defined employees ‘typology’ (only 5 percent are likely to be career hunters, and 11 percent managers), and offered 10 ‘golden insights’ into successful recruitment today – including being realistic and patient, daring to dream, having an eye for diversity, thinking global, and not fearing the future. In the label industry, he adjured delegates to raise their employer branding to encourage recruitment, in an arena where M&A activity is increasing.
‘What does Industry 4.0 mean for the manufacturing process?’ was the subject addressed by Stephan Lechel, a partner in Porsche Consulting and leader of the company’s Competence Center. Specifically, he focused on the impact of digital media – a true cultural change – on the print industry as a whole, and implications for the future. ‘What can be digital, will be digital’ was his uncompromising statement, and he urged delegates: ‘Disrupt yourself, before others do.’ Digitization ‘is not just a trend, but a real revolution’, he underlined, demonstrating how successful companies that are digital champions have been in the business arena. In the
Fortune 500 listing of leading companies, five of the 10 most valuable companies come from the American digital economy. For print and packaging, digital technology at all levels must become a key feature of the business, and while some 75 percent of companies surveyed in Porsche Consulting’s recent management survey indicated they agreed on this point, only 35 percent already have a digitization strategy – and only 30 percent have the required competence to achieve it, although customer requirements are changing rapidly. Expectations have changed dramatically: brand owners demand high levels of customization, choices and updates, so companies in the business of labels and packaging must embrace digitization in a variety of forms in their print offering.
Andy Hobsbawm, co-founder and chief marketing officer of smart products platform Evrythng, discussed the Internet of Things.
Its inception has meant, he said, that ‘the age of smart products is happening now’, and it has brought enormous change to brand owners in terms of customer interaction and resultant data collection, as well as huge opportunities in terms of supply chain efficiencies, stock monitoring, and reduced counterfeiting and grey market losses. The impact on the supply chain of these ‘product ecosystems’ is enormous, and Hobsbawm advised delegates ‘to stop thinking about what you do as purely physical’. Labels and packaging are just beginning to explore the available technologies – among them augmented reality, sensors, printed electronics, batch/SKU QR codes – that can make packaging and labels smart.
Direct threat?
The challenging tone of the event was set by an eagerly anticipated discussion of a possible threat to the label industry from direct-to-container (DTC) technologies led by Corey Reardon, president and CEO of research consultancy AWA.
Direct print is nothing new of course. Beverage and aerosol cans, cartons containing liquids and foods, flexible packaging for food, beverages and chemicals and screen printed products – typically beverage and chemicals products – are established direct print items for package print buyers.
Direct digital printing of molded containers is the new kid on this block.
The companies pushing the technology hardest are the filling/capping machinery manufacturers Krones and KHS, with others assessing the technology. Typically, this means adding CMYK+White Xaar TF printheads to the filling machine, so the container is decorated, filled and capped in a single operation.
The Xaar heads uses UV inks qualified for low migration on a variety of container types including PET, HD-PE and PP, with UV LED curing systems under development. Both cylindrical and complex shapes can be handled.
Reardon told delegates the main targets for Krones and KHS are high profile brand owners in the beverage and home/personal care sector. Both companies are not shy about pushing the advantages of direct-to-container technology: cost savings by elimination of label materials; exact production quantities on demand; ability to handle a wide variety of rigid and semi-rigid container materials with high quality graphics registered to shape; variable data printing for personalization or customization; short changeover times waste; reduction in time to market; localized production independent of the label supply chain.
However, as Reardon pointed out, these factors are balanced by important disadvantages. Perhaps most important, ink costs are ‘too high,’ said Reardon. ‘The price will come down with more use and more inks suppliers, but are ink companies prepared to undertake future development for this market?’ Another potential question mark hangs over the recyclability of direct printed containers, and this is now undergoing evaluation. Other disadvantages include the high capital cost of the equipment and relatively slow line speeds – although Reardon said this will be addressed with the next generation of equipment. A major drawback for the personal care market is that it is not possible to print metallics with UV inkjet.
End users seem to be increasingly aware of direct-to-container technologies, according to an AWA sample: almost half of respondents in the key H&PC, beverage and food sectors ‘know about and are interested’ in DTC technology.
In the Q+A session that followed, attendees cast doubt on the DTC proposition. Tarsus Labels and Packaging group chairman Mike Fairley pointed out that direct decoration ‘can’t add the value of foiling and embossing, and so on, to higher added value health and beauty products, or the tamper-evidence provided by sleeves.’
Federico d’Annunzio, technology director at Bobst, said DTC machines ‘are so slow you would need two machines to match the speed of one label applicator. And there are lengthy set-up times for different container shapes on a direct print machine.’
Europe surges ahead
Finat managing director Jules Lejeune presented his annual assessment of the European pressure sensitive label industry, noting a healthy growth rate of over five percent in 2016: ‘The strong recovery since 2012 continues.’ Consumption of PS label materials has sat consistently above European GDP growth since 2012.
According to Finat’s figures total European PS label consumption for 2016 was 7.1 billion sqm – more than double what it was 20 years ago. Lejeune noted that label roll growth closely tracks GDP growth, and in fact can be seen as a leading indicator.
Filmic roll label materials continue to grow at the expense of paper, now representing more than 25 percent of total demand against 15 percent in 2000. Filmic materials grew by 5.1 percent in 2016.
Eastern and Southern Europe continue to be Europe’s growth drivers. Eastern Europe now accounts for more than one fifth of total European demand, double the 2003 figure. Romania and Hungary alone posted above 60 percent growth between 2010 and today, and Poland an astonishing 70 percent. In absolute terms, however, growth this decade has been dominated by southern Europe, particularly Turkey, Italy and Spain. Turkey is now among the top 10 European label markets.
At the same time, the established markets of Central Europe and UK/Ireland have shown only moderate growth, with an actual decline in Scandinavia (except Sweden).
These figures of course represent just PS consumption. It is worth noting that more than 20 percent of converters surveyed are either offering, or considering offering at least one non self-adhesive technology – flexibles, sleeves, IML or cartons – meaning the total level of activity is considerably higher.
On the Radar
Finat’s annual Radar survey looks at trends among converters and end users. Starting with end users, half of respondents indicated that label procurement will increase in 2017, an encouraging figure, although down from 65 percent two years ago. Almost 70 percent said they have no intention of moving from self-adhesive to other packaging formats.
Despite fears that reverse auctions would come to dominate the industry, 85 percent of end users say they plan to stay with their current label vendor – up from 75 percent two years ago. More depressing is that the food, HABA/personal care and beverage sectors, which represent the bulk of label consumption, are most likely to put business out to bid.
The survey did pick up on a continuing trend to shift sourcing from Western Europe, with 40 percent of respondents indicating a move to Eastern Europe, China and India.
The Radar converting market survey reflects the wider industry’s robust health. Sales growth in all vertical markets increased compared to the 2015 survey, averaging +7.3 percent in all regions between 2013-16. This is consistent with a reported average profitability growth of 7.8 percent.
As one would expect, digitally produced labels now have a higher share of the total revenue mix, as do high-end combination labels and ‘adjacent’ (non-PS) narrow web markets.
Brexit appears to be having an early effect, with UK converters reported to be ‘on fire’ in 2016, arguably due to the precipitous decline of sterling against the Euro.
The Radar survey found a continued decline in run sizes for conventionally printed labels, while there was a marked increase in average digital run sizes driven by the increased installation base and higher speeds of inkjet presses. Average run length for conventional was reported at 4.5-5,000 linear meters and 850 linear meters for digital.
There is certainly a lot of scope for increased efficiency in conventional press use, with current downtime for set-up and changeovers ranging between 22.5-35 percent. Next year’s survey will include downtime rates for digital presses – a welcome development given the troubling results of the LPC digital survey in this respect.
Revenues per employee ranged between 140,000-210,000 EUR, with a European average amount of 167,000 EUR.
A particularly interesting Radar question concerns most significant day-to-day challenges. At number one is price reduction pressures from customers, followed by, in order: dealing with shorter lead times; finding qualified press operators; raw material price increases; recruiting qualified personnel (other than press operators); accounts payable extending to an ‘unreasonable’ time; lost business to foreign markets; and access to capital.
Digital survey
Finat commissioned consultancy LPC to examine the digital label market in Europe. The headline figure puts the total value (converter sales) of digital labels in 2016 at 1.57 billion EUR. While digital sales represent 7.2 percent of global label market value, this rises to 9.7 percent in Europe. The figure varies by end user category. In the two largest sectors for label consumption, food and beverage, digital represents respectively 9.2 and 7.4 percent of total value. In the smaller HABA market digital represents an astonishing 18.2 percent, and 19.5 percent in pharma. The figure for household chemicals is 8.8 percent and 11.9 percent for industrial chemicals, with auto at 4.9 percent.
The LPC survey finds the total installed base of digital presses in Europe is 2,000, of which one quarter is inkjet or hybrid inkjet/flexo. Last year saw between 170-180 new digital presses installed in Europe, mostly in the five biggest label markets.
Looking ahead to 2022, the survey predicts toner-based installations growing at 8 percent a year and inkjet-hybrid at 14.5 percent – meaning toner-based technologies will still be dominant at around two-thirds of all digital installations in 2022.
The survey finds that of those planning further digital investments, almost half plan to buy inkjet (one quarter of the sample currently have inkjet presses).
At least one-fifth of the converters surveyed have no plans to purchase more digital presses.
What converters are prepared to spend on digital hardware compares quite closely with what they would pay for conventional equipment, with 14 percent paying over one million EUR and a further 18 percent investing between 750,000–1 million (it is not clear if this also includes converting equipment).
Concluding with digital pain points, the LPC survey puts total cost of ownership at number one. This probably reflects the greater cost of consumables compared to conventional inks, as well as the number two listed pain point – ‘Press downtime due to service issues’.
There is also concern (number 3) about finding enough business to fill digital capacity, related to a concern that ‘My sales people don’t know how to sell digital labels’.
The digital process concerns are interesting. At number four is ‘finishing requirements’, which definitely requires more investigation. Printing high opacity whites figures next, which seems to run contrary to the digital supplier industry’s claims about matching UV flexo and even screen opacities. This concern is clearly related to pain point seven – difficulty with transparent films.
Color matching is listed at number six, but it is not clear if this is matching with end users’ color expectations or with conventional print processes.
A final survey question on the attitude of end users to digital print is inconclusive. It seems that very few customers are requesting digital, and of those that do, most seem not to understand what the digital process can deliver in terms of value.
The Finat business debate
Paul de Ruijter returned to the platform to present delegates’ suggested outcomes for the future of the imaginary company featured in the prior day’s workshop, and then welcomed four high-powered representatives of the global label and packaging industry for the Finat Business Debate: Chris Ellison, owner of OPM (Labels and Packaging) Group and Finat president; Geoff Martin, president, CCL Label; Adrian Tippenhauer, All4Labels; and Mike Henry, executive vice president, Constantia Flexibles Label Division. The four panelists talked about the current business environment and answered delegates’ questions.
Is artificial intelligence a challenge or an opportunity? Geoff Martin commented: ‘The industry is going to be driven by customers like Apple – these techno companies have a different mindset’. ‘The disruptive side is more at the brand owners’ end of the business,’ said Mike Henry.
Adrian Tippenhauer agreed, but added: ‘I don’t believe digital print will replace traditional print in the next five years. Our response should be to understand what the customer needs, and look for an expert who can do it, rather than invest in our own platform.’ Chris Ellison saw the focus of the business operation changing. ‘We have to be investing in more IT people and the people to work in this industry, constantly investing in training, and moving people around so they can multi-task.’
‘How can you prepare for a talent war?’ asked Paul de Ruijter, returning to one of the key issues impacting the label industry today: recruitment. ‘We have to “chase” the people,’ said Chris Ellison. Geoff Martin commented: ‘The level of hunger to learn is less in the EU and the US than in the emerging economies,’ adding that Germany has the best apprenticeship scheme in Europe. Adrian Tippenhauer endorsed this view and said: ‘In our company, we are not shy of having young people take responsibility.’ Mike Henry said: ‘Once you get them in the door, it’s OK! It’s a great business to be in.’
Keynote: the wider context
From an inside view of the industry the agenda moved to an evaluation of the wider context: the future of the European economic and political landscape. This was presented by Joschka Fischer, Vice Chancellor and Minister of Foreign Affairs in Germany 1998-2005, currently co-chair of the executive board of the European Council on Foreign Relations, and also running a business consultancy in Berlin. One of the most highly-respected statesmen of recent years, Joschka Fischer connected past and present to create an awe-inspiring vision of the future centered on Europe’s need to bring together all its different national cultures. ‘Europe means diversity,’ he underlined, ‘in a united front, to peacefully protect and promote its continued success and happiness. Because, after all, there will be a shift of power from west to east – and who will then take care of us? Our common destiny will be very important.’
Chris Ellison, the new Finat president, outlines industry challenges and the agenda for his presidency here
Stay up to date
Subscribe to the free Label News newsletter and receive the latest content every week. We'll never share your email address.